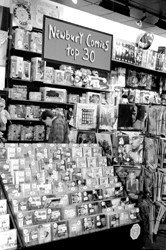
Step into a Newbury Comics store, and you’re bombarded with pop culture: rack
after rack of the latest rock, rap and indie releases, DVDs, magazines, posters,
hats, action figures, bobbleheads, and every manner of kooky toys and collectibles.
The shoppers range from teenage mall rats, to middle-age parents, to connoisseurs seeking hard-to-find titles. Most pick up a mix of items. And despite all the doom-and-gloom talk about retail music sales, quite a few buy CDs.
Newbury Comics is aggressive in its pricing, charging as little as $9.99 and mostly under $14 for new releases and other high-demand titles. CEO Duncan Browne acknowledged that, on some titles, the store loses money. But the prices do “stimulate” customers, and in the big picture, Newbury Comics comes out ahead.
Music sales at the New England music chain are up about 5 percent from last year, Browne said. Nationally, the International Federation of the Phonographic Industry says U.S. sales were up 5 percent by units in the first half of 2004, and 3.9 percent by dollar value. In the first half of 2003, they had dropped by 12 percent.
The progress should continue in the second half of 2004, the IFPI predicted. The period usually accounts for three-fifths of sales, and it should be boosted by several big-name releases, from Britney Spears, to Eminem, Nelly, Shania Twain and U2.
But the gap between the rise in unit sales and dollars shows how tough the business remains. And for music stores, the trends are still unnerving: While as recently as 1998, the Recording Industry Association of America found that 50.8 percent of consumers got their music at record stores, by 2003 it was only 33.2 percent.
Rhode Islanders needn’t look far to see the trend. While College Hill, that bustling hub of music-loving students, once had a large Sam Goody store, plus the indie lovers’ In Your Ear and vinyl-focused Tom’s Tracks, only the latter remains.
At first, industry leaders blamed first Web-based retailers such as CDNow and Amazon.com; then they blamed Napster. The RIAA’s figures, however, show that at least at this point, Wal-Mart and other big stores have done more to kill record stores. Between 1998 and 2003, non-specialty stores’ share of music buyers grew from 34.4 percent to 52.8 percent. Internet sales, by contrast, rose from 1.1 percent to 5 percent of the market.
As for iTunes, Rhapsody, Musicmatch and the rest of the legal download market, it’s still tiny: $36 million in 2003, according to Forrester Research, compared with $10.66 billion in CD sales in the United States. But downloads are growing rapidly; Forrester analyst Josh Bernoff has predicted they will produce $201 million this year. By 2008, Bernoff says, downloads will rise to $3.2 billion, while CD sales drop to $9.3 billion.
“Music labels should get out of the plastic business: Spend less energy on manufacturing and distributing a shrinking number of CDs, and focus more on the new source of growth – downloads and subscriptions,” Bernoff advised.
Jim Donio, executive director of the National Association of Recording Merchandisers, isn’t ready to give up on CDs, which he noted are still expected to make up the bulk of the music market for many years. Still, “we can’t keep our heads in the sand,” Donio said. Stores that want to survive can’t just keep putting CDs on racks; the future is in creating “experience destinations,” he said, with features such as on-demand CD burning and a diversified inventory.
“You have to have people to want to come and want to stay and buy,” Donio said. That may mean going beyond music: “We added lifestyle products, we added DVDs, we added coffee bars. We added, in some cases, clothing and cosmetics and other items.”
New formats and “added value” features also attract customers, Donio said. The IFPA’s half-year figures show worldwide, audio sales fell by 2.7 percent by value, but music DVDs increased 26.6 percent. The next wave may be the DualDisc, a two-sided disc with a CD on one side and a DVD on the other that several labels plan to launch. (On the other end of the spectrum, the CD singles market is virtually dead, Donio said; one estimate puts the download-to-CD ratio at 10:1.)
At Newbury Comics, Browne said plans are in the works to set up listening booths that double as CD-burning stations, both to encourage people to explore new music, and to expand the store’s catalog without adding physical inventory.
Much of the chain’s strategy, however, is built on its longstanding strengths, Browne said. Newbury Comics has always been aggressive on music prices; it’s always had an offbeat, hip feel to its stores, and it’s always hired salespeople who love music and pop culture and can share their enthusiasm and expertise with customers. “We want people coming in and feeling like they’re going to talk to kindred spirits,” he said.
Newbury Comics also has an advantage in that, unlike many record stores, it’s always carried a variety of products, Browne said, so it’s not having to change its identity to stay fresh. The non-music items help offset losses from low CD prices, and they attract a whole extra layer of customers, he said – even 10-year-olds who come for Japanese collectible cards, and whose moms may just pick up some CDs as well.
The result is that while Newbury Comics isn’t awash in profits, it’s doing well enough that it’s grown to 24 stores, and wants to expand more. “So in this environment where other music retailers are closing their stores or reengineering their model, we are finding new opportunities,” Browne said.
On a national scale, Donio said, there’s still plenty of potential for music retailers, even the brick-and-mortar type. The key, he said, is to be versatile, keep the music fresh and diverse, and reach out to a wide range of potential buyers – not just teens and college-age download fans, but also their parents.
“If the music is good, and if it’s marketed to the right audience, people will buy it,” he said. “With all the travails that we’ve had, people are still interested in music. People love music.”