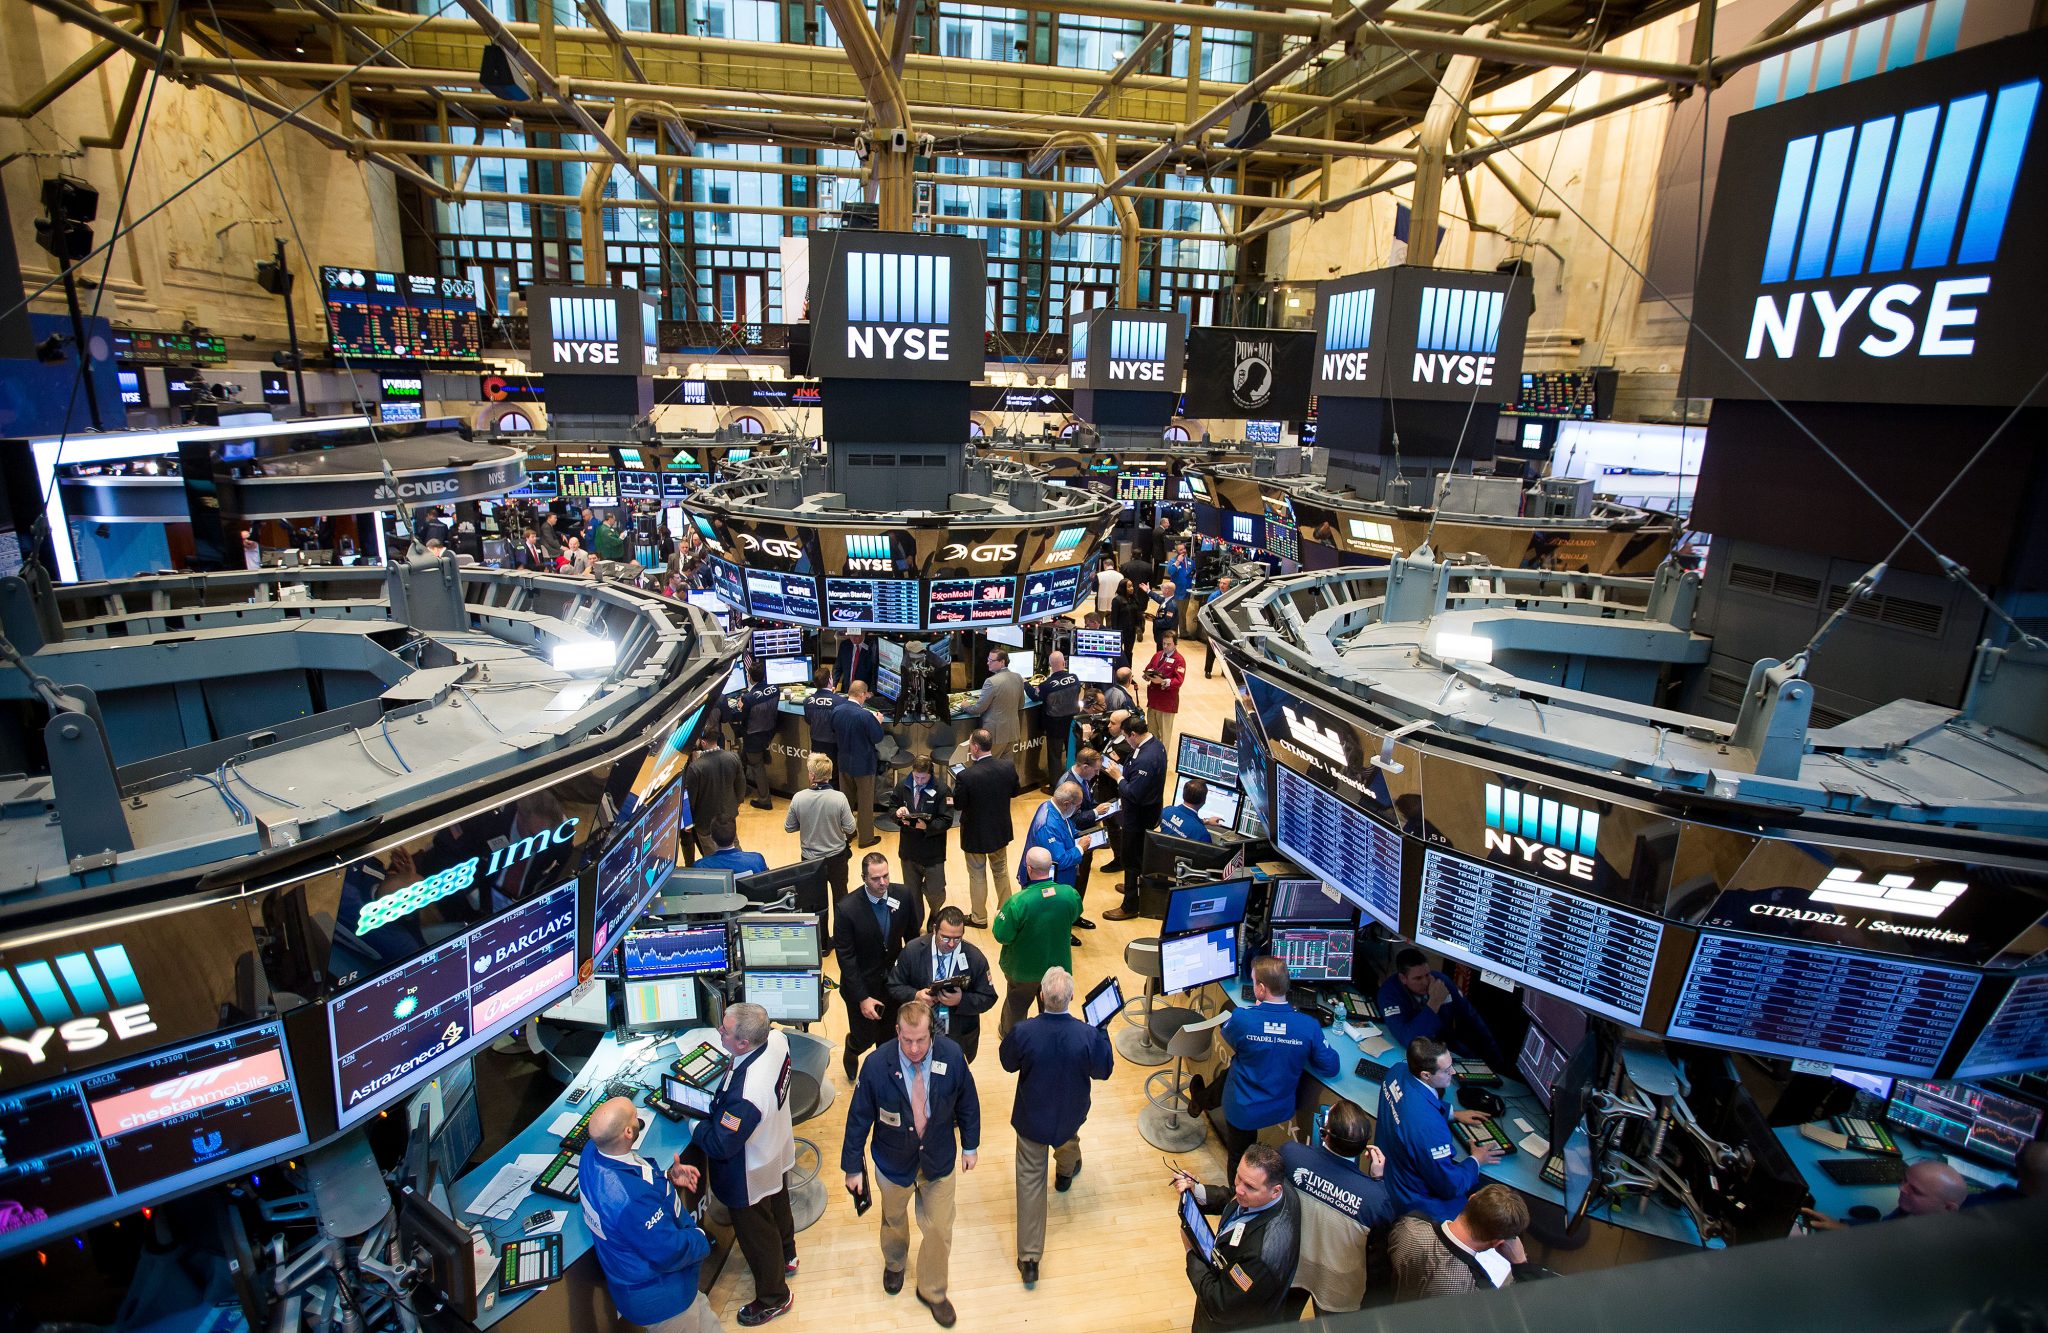
NEW YORK – The sell-off in United States stocks accelerated, wiping out gains for the year in both the S&P 500 Index and the Dow Jones Industrial Average, as mixed corporate earnings and weak housing data fueled anxiety that rising prices will crimp economic growth. Treasuries rallied for a second day on demand for haven assets.
The S&P extended its October rout to 8.8 percent, making it the worst month since February 2009. Disappointing earnings from AT&T and Texas Instruments drove declines in the communications and semiconductor groups, offsetting a promising outlook from Boeing. The Dow tumbled 600 points, and the Nasdaq Composite Index lapsed into a correction from it’s record closing high in August.
Building a Strong Data Foundation in the Age of AI
Artificial intelligence (AI) has become a key priority in the boardroom and across management —…
Learn More
Amid the flood of earnings that will bring reports from Alphabet, Intel and Amazon.com on Thursday, economic data continues to underwhelm, particularly on the rate-sensitive housing front. New home sales sank again, sending battered homebuilders lower. Fragile market sentiment is also working through reports that potential bombs were sent to two former U.S. presidents and the New York headquarters of CNN.
“There’s just right now a heightened sensitivity to what can go wrong,” Kate Warne, investment strategist at Edward D. Jones & Co., said in an interview at Bloomberg’s New York headquarters. “So we will have more of these days where stocks move a lot within the day as everyone’s trying to sort through what do today’s reports mean.”
European politics were also in focus, with Italian Prime Minister Giuseppe Conte doubling down on his government’s budget and U.K. Prime Minister Theresa May’s cabinet descending into conflict. The pound weakened, and the region’s bonds rallied. The euro dropped following disappointing manufacturing data.
“Right now markets are still trying to reprice,” said Chris Zaccarelli, chief investment officer at the Independent Advisor Alliance. “What’s happening with earnings is exaggerating market moves.”
Elsewhere, oil fell to lowest in almost two-months even after a pledge by Saudi Arabia to meet any shortfall that materializes from Iranian sanctions.
Here are some key events coming up this week:
Earnings season rolls on with notable highlights including Twitter, UBS and Total. Monetary policy decisions are due in Sweden and Canada. ECB policy makers could on Thursday confirm that asset purchases will end this year, reiterating its pledge to keep interest rates at record lows through summer 2019. President Mario Draghi will hold a press conference. U.S. gross domestic product growth may have slowed in the third quarter, yet remained near its best pace since mid-2015, according to forecasts ahead of Friday’s release.
These are the main moves in markets:
Stocks
The S&P 500 dropped 3.1 percent to 2,656.29 as of 4:02 p.m. in New York, while the Dow Jones Industrial Average slumped 2.4 percent to 24,584.71 and the Nasdaq Composite Index tumbled 4.4 percent to 7,108.40. The Stoxx Europe 600 slipped 0.2 percent, the sixth consecutive decline. The U.K.’s FTSE 100 gained 0.1 percent, the first increase in three days. Germany’s DAX Index slumped 0.7 percent, the sixth straight drop. The MSCI Emerging Market Index eased 0.7 percent. The MSCI Asia Pacific Index slumped 0.4 percent.
Currencies
The Bloomberg Dollar Spot Index was 0.4 percent stronger, reaching the highest level of the year. The euro declined 0.7 percent to $1.1391. The British pound fell 0.7 percent to $1.2898. The Japanese yen was little changed at 112.39 per dollar.
Bonds
The yield on 10-year Treasuries dropped seven basis points to 3.10 percent, while the two-year note yield fell five basis points to 2.83 percent. Germany’s 10-year yield fell one basis point to 0.40 percent.
Commodities
West Texas Intermediate crude fell 0.2 percent to $66.30 a barrel. Gold rose 0.2 percent to $1,233.03 an ounce.
Vildana Hajric and Sarah Ponczek are reporters for Bloomberg News.