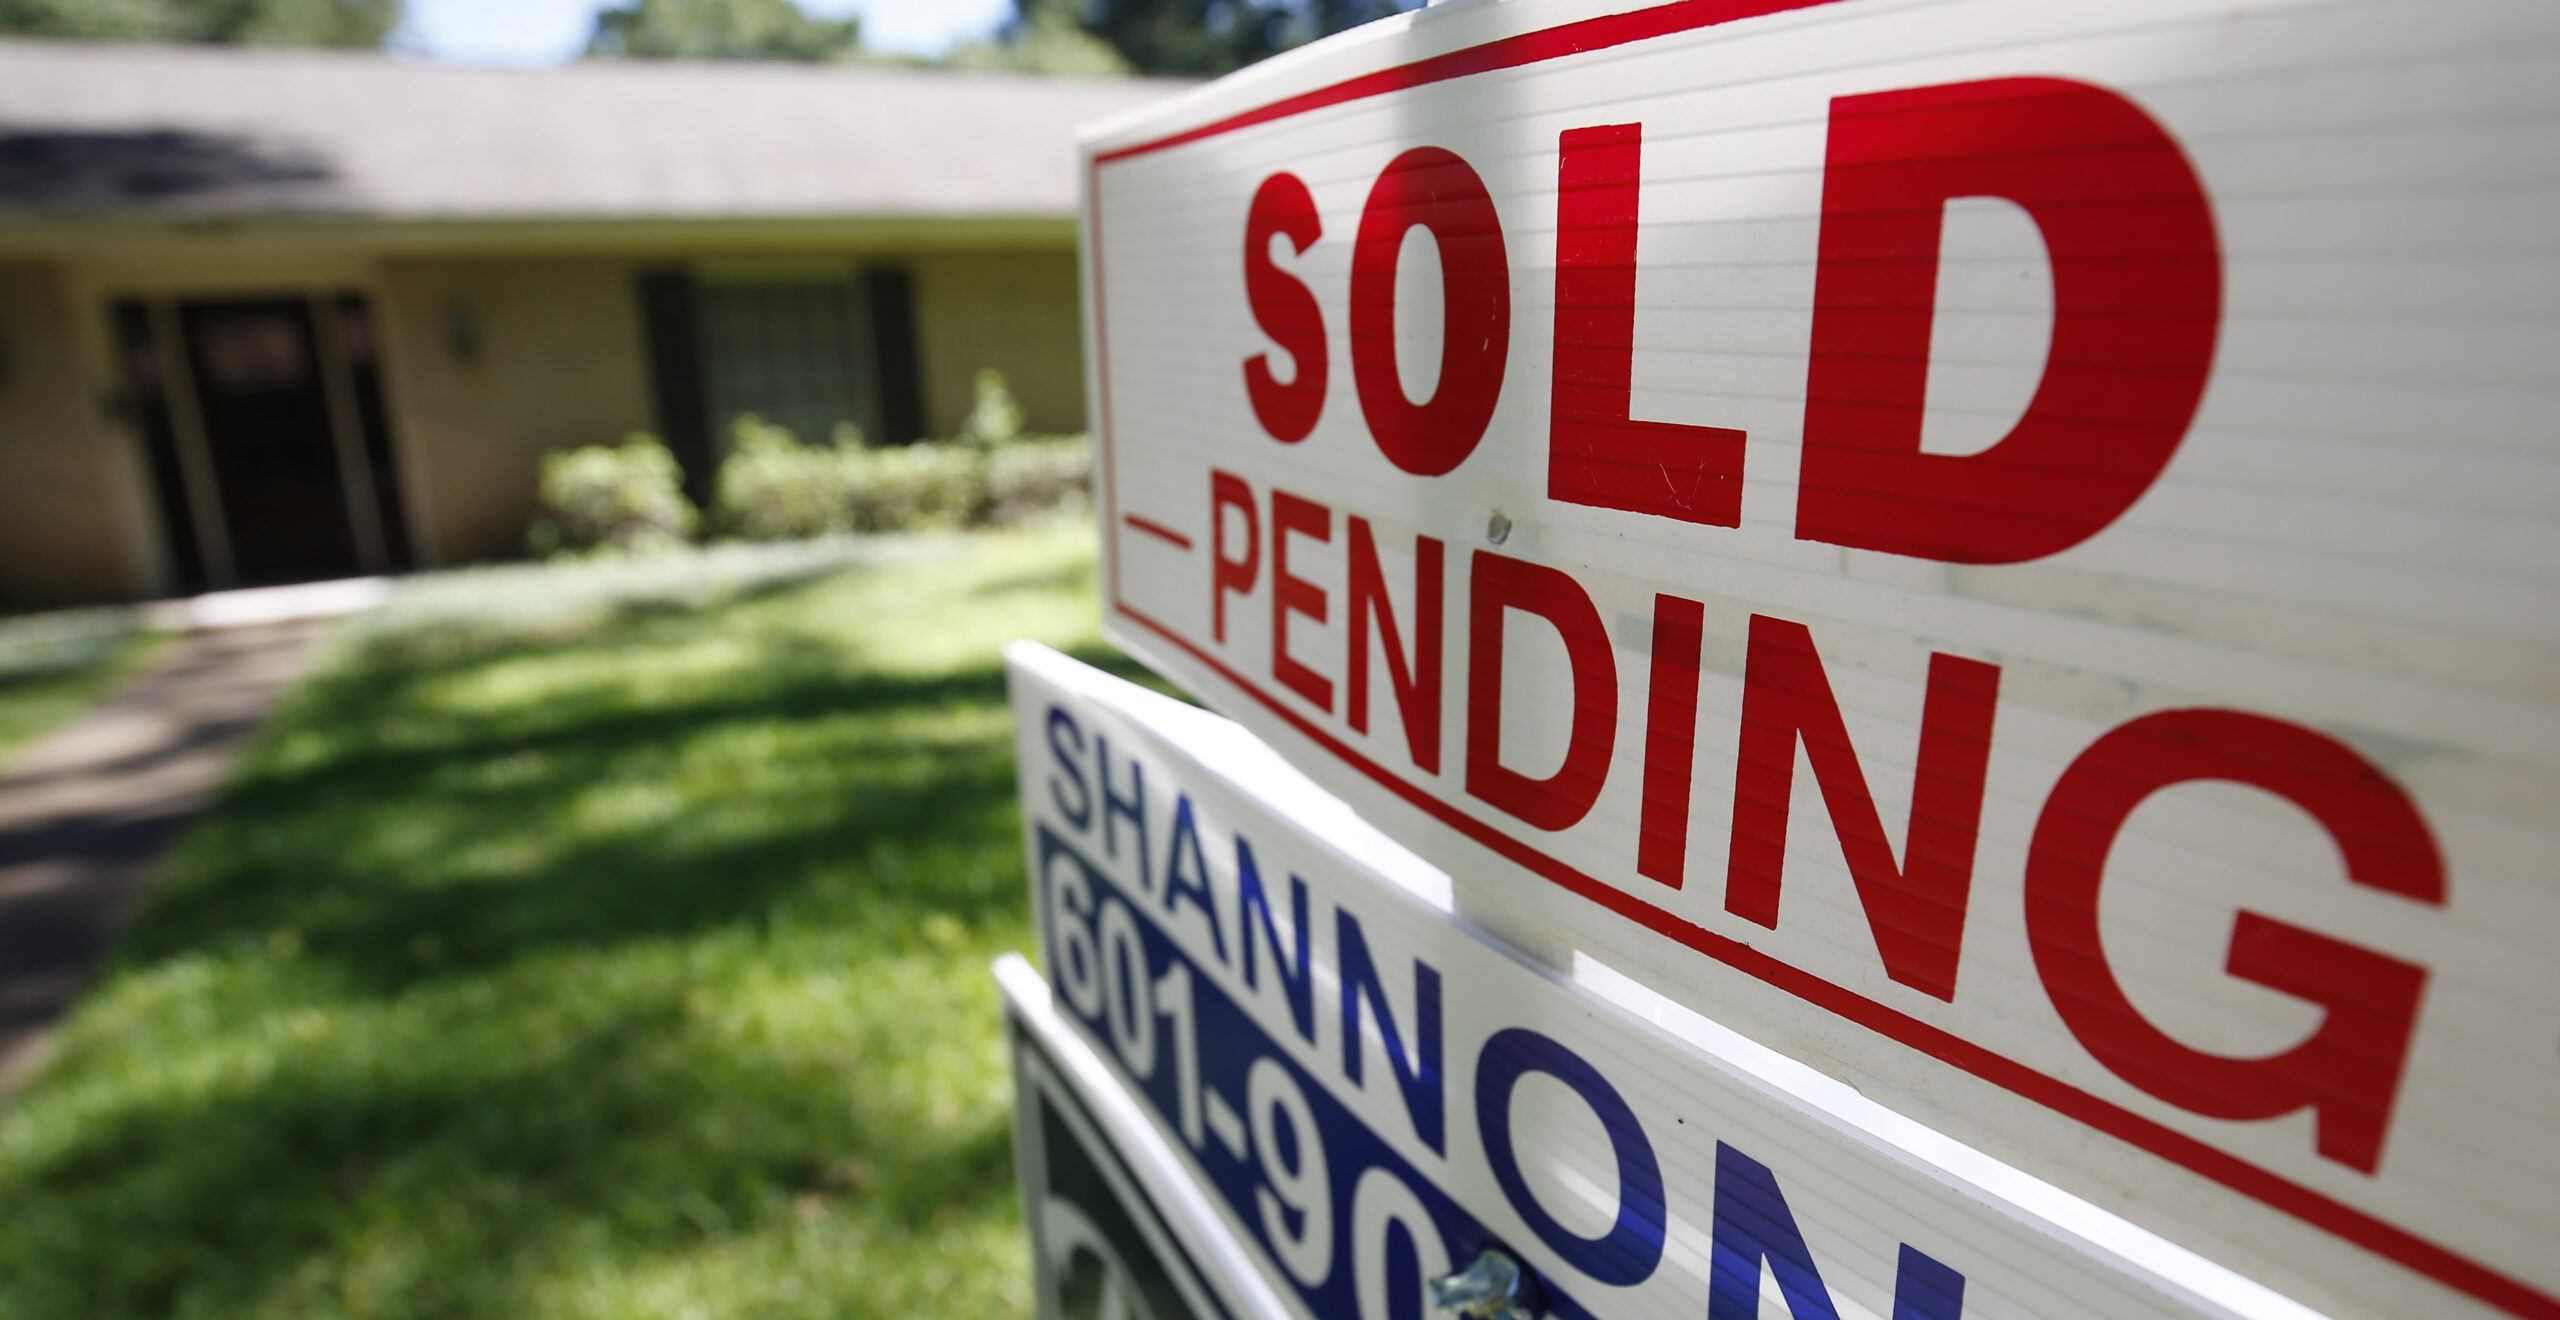
PROVIDENCE – The mortgage delinquency rate of 30 days or more in Rhode Island was 6.3% in August, a rise from 4.5% one year prior, CoreLogic said on Tuesday.
Nationally, the mortgage delinquency rate was 6.6%, a rise from 3.7% in August 2019.
Rhode Island's Market Has Changed. Developers, Builders, Investors and Sellers Must Change With It.
By Emilio DiSpirito IV License Partner | Engel & Völkers Oceanside Leader | The DiSpirito…
Learn More
Rhode Island’s mortgage delinquency rate was the second highest in New England, only lower than Connecticut.
Other New England mortgage delinquency rates:
- Connecticut: 8.4%, rise from 4.8% one year prior
- Massachusetts: 5.6%, a rise from 3.6% one year prior
- Maine: 6.3%, a rose from 4.5% one year prior
- New Hampshire: 4.8%, a 1.7 percentage point rise year over year
- Vermont: 5.3%, a rise from 3.2% one year prior
Rhode Island’s rate of serious delinquency, or payments 90 days or more past due, accounted for 4% of all mortgages, a rise from 1.6% one year prior. The state’s foreclosure rate, however, had declined slightly in that time, from 0.5% to 0.4%.
“Five months into the pandemic, the 150-day delinquency rate for August spiked to 1.2%,” said Frank Nothaft, chief economist at CoreLogic. “This was the highest rate in more than 21 years and double the January 2010 peak during the home-price bust. The spike in delinquency was all the more stunning given the generational low of 0.08% in March and April.”
Nationally, the serious delinquency rate was 4.3%, a rise from 3.7% one year prior. The national foreclosure rate was 0.3%, a decline from 0.4% in August 2019.
“Forbearance programs continue to reduce the flow of homes into foreclosure and distressed sales and has been the key to helping many families who have been particularly hard hit by the pandemic,” said Frank Martell, president and CEO of CoreLogic. “Even though foreclosure rates are at a historic low, the spike in 150-day, past-due loans points to bumpy waters ahead.”