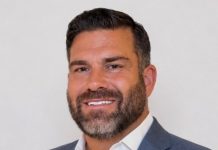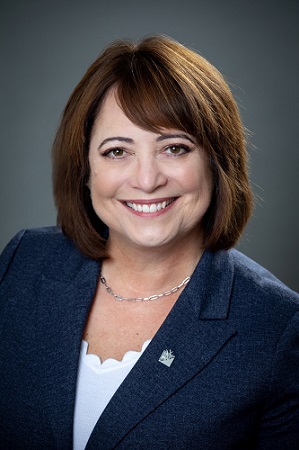
Colleen Gouveia Moulton was recently named senior vice president and director of commercial banking for BankNewport. She has more than 30 years of experience in the industry, including previous roles as a senior loan officer for Rockland Trust Co.’s commercial lending division and as senior vice president and client manager for Bank of America Corp. She has a bachelor’s degree in accounting from Rhode Island College and a master’s degree in business administration from the University of Rhode Island.
PBN: What do you see as the biggest opportunities for BankNewport to grow market share?
Selling Luxury Real Estate Requires More Than Exposure
By Emilio DiSpirito IV License Partner | Private Office Advisor Engel & Völkers Oceanside www.DiSpiritoteam.com…
Learn More
MOULTON: Our primary differentiators are the size of our institution and the fact that we have a local management team. That we make all lending decisions right here in Rhode Island allows us to react quickly to shifts in market conditions and to meet the ever-changing needs and preferences of our customers.
Our commitment to technology while maintaining our personal touch will continue to help us grow. BankNewport has recently made investments in digital platforms that create speed in delivery while maintaining a strong focus on customer relationships. This approach maximizes efficiency and enhances digital customer engagement.
PBN: How important are face-to-face interactions in the commercial banking space? Does it seem more important than with retail customers? How should BankNewport balance growth through digital platforms and in-person interactions?
MOULTON: BankNewport does business with people, not entities, and business is about building relationships, which is best done in person. As an organization, we pride ourselves on providing an unparalleled customer experience, and we are always looking for opportunities to enhance that experience, whether in person or digitally.
PBN: What benefits or advantages does BankNewport have as a community lender versus a regional or national bank when it comes to commercial banking? What disadvantages or challenges might that bring?
MOULTON: Lending decisions at BankNewport are made locally, and therefore, quickly. Because we live and work in the communities we serve, our team tends to have a better understanding of the challenges and opportunities that our customers face, resulting in stronger relationships where we can provide better insight and customer service.
PBN: How have rising interest rates and economic uncertainty impacted the bank’s business clients and, in turn, its own commercial banking lines?
MOULTON: Recent interest rate increases have provided for a less-predictive economy, which in turn creates a multitude of complexities for our customers. Understanding these uncertainties, BankNewport’s lending team helps guide our business customers. We offer multiple loan structures, including SBA [U.S. Small Business Administration] guaranteed loans and many interest rates and payment options.
PBN: What are your top three goals for your first year?
MOULTON: My top three priorities in my first year are: first, to support the bank’s strategic growth initiatives in the commercial space, including the diversification of our loan portfolio; second, to facilitate the rollout of new technology and digital services to our commercial clients; and third, to grow our commercial loan portfolio through providing exceptional coaching and guidance for our team of commercial bankers.
Nancy Lavin is a PBN staff writer. You may reach her at Lavin@PBN.com.