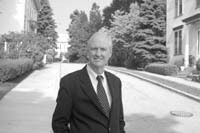
PBN: What do you see as your mission as president of the Rhode Island Association of Realtors?
YOUNG: There are a couple of things we’re working on. We’re really looking at how the association serves both the Realtor and the consumer, and how we can improve upon that service. It’s a challenging time to be president of the association, mainly because all markets are changing so quickly, and we’re certainly seeing a lot of changes in the real estate sales market. My role is to try to make sure we stay one step ahead of changes that are going on in both the marketplace and in technology. The biggest challenge is that the consumer is very smart today, very well-informed, and very Internet-oriented. But we’re keeping up, so that we can stay in the middle of the transaction. We don’t want to lose our role of being a very important element in the home-sale transaction.
PBN: How would you characterize the real estate market in Rhode Island right now? Nationally, there’s talk of a market bubble or a series of bubbles in certain regions. Federal Reserve Chairman Alan Greenspan has recently talked more than once of a “froth” that concerns him. Do you see that happening here?
YOUNG: The Rhode Island market, and specifically Greater Providence and our waterfront areas around Narragansett Bay, is one of the five or eight fastest-growing markets in the United States. And it’s been that way for the last five or six years – we’ve seen price rises overall at close to 20 percent a year. The median sale price of a home has actually doubled in the last five years. At this point we feel the market will continue to prosper, but that certain forces are going to moderate those increases of both prices and growth. We do not see prices going down, but we do see them increasing at lesser amounts – maybe around 9 or 10 percent a year instead of 18 to 20 percent.
Cybersecurity Awareness Month: What to Do When Your Identity Is Stolen
In recognition of Cybersecurity Awareness Month, it is important to remember that identity theft affects…
Learn More
PBN: Are you concerned by the greater percentage of homeowners who have entered the market in recent years with the use of adjustable rate mortgages or mortgages that allowed them to put no money down? Could a lot of people be facing foreclosure if interest rates continue to rise or the overall economy takes a turn for the worse?
YOUNG: We have seen a lot of growth in prices, but the Rhode Island jobs situation seems strong, and national economists feel that Rhode Island is still a relative bargain in comparison to, say, Massachusetts or Long Island or Connecticut. Also, mortgage rates have been very low for a long time now. For the moment, mortgage rates are still inexpensive. And while it’s true that many people have utilized adjustable rate mortgages, most of those mortgages are fixed for probably five or 10 years, with fixed payment amounts.
PBN: The arrival of hurricane season is a reminder that waterfront homeowners are seeing the cost of insuring their homes rising. Is that something that’s going to become more of a concern in the future?
YOUNG: We’ve seen this problem arising in Florida and California and other areas near the coast, and we would predict that it’s going to become more of a concern here in Rhode Island. Flood insurance – especially after the hurricanes – and just normal homeowners insurance is going to become more problematical. There are discussions of making insurance part of the transaction when putting a sale together, making it as important as the mortgage or even the home inspections – because it’s something that homebuyers really need to look at early in the process of buying a house.
PBN: One thing that homeowners all talk about in Rhode Island is the state’s high property taxes. Are there certain things that can and should be done legislatively to ease the property tax burden for homeowners here?
YOUNG: I think the governor realizes that the municipalities are too dependent on taxes and that the state is as well, and that there will be changes – hopefully in the near term. For the moment we are not competitive with our neighboring states in terms of property taxes.
PBN: You recently returned from a lobbying trip to Washington, D.C., as part of a delegation of the National Association of Realtors. What were you pressing for in Washington?
YOUNG: The National Association of Realtors has been fending off interest in our industry from the banks. The national banks, the big money-center banks, would love to get into real estate brokerage. They want to get into real estate to get the information on people. It’s all about information for the banks, and people buying homes is a very good sector to find that information. So part of our role at the state level has been to work with our congressmen and senators to try to keep them out. We’re working hard to utilize federal legislation to keep them in the financial business and not in the real estate service business. We don’t feel the banks have the same mentality, the same culture that we do in terms of working in the real estate brokerage service business.