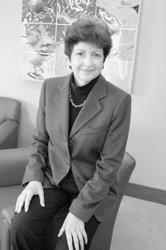
Merrill W. Sherman
Position: President and CEO, Bancorp Rhode
Island Inc.
Background: Sherman spearheaded the creation of Bank Rhode Island in
1996, when the merger of Fleet and Shawmut banks required them to divest some
of their Rhode Island assets. Before leading BankRI, Sherman spent 17 years
as a lawyer in Providence, and served as president and CEO of two other New
England banks. Sherman also serves on several corporate boards and is involved
in several nonprofit groups, including Crossroads Rhode Island, whose board
she chairs, and Rhode Island School of Design.
Selling Luxury Real Estate Requires More Than Exposure
By Emilio DiSpirito IV License Partner | Private Office Advisor Engel & Völkers Oceanside www.DiSpiritoteam.com…
Learn More
Education: Bachelor’s from Mount Holyoke College; law degree from the
University of Denver College of Law
Residence: Providence
Age: 56
Bank Rhode Island, the state’s fifth-largest bank, has grown at a vigorous
pace since its creation in 1996, with particular strength in business banking.
It has grown its commercial loans at a rate of about 20 percent per year, with
an 18-percent jump in the first nine months of 2004. Net earnings for the third
quarter were a record $2.2 million. Gearing up for more growth, the company
has expanded its leadership team, adding a chief operating officer and hiring
a Fleet Financial Group veteran as treasurer.
PBN: Let’s start by looking at the market in Rhode Island right now. Is it a good time for banking?
SHERMAN: I think it’s always a good time for banking. It’s a basic service, and it meets a basic need, so it’s not an industry that you think of as going away. And I think banks have done pretty well in terms of staying on top of trends and trying to meet people’s needs. So as an industry I’m very high on banking. In Rhode Island we have one of the more interesting marketplaces in the country. The larger institutions in the region have incredibly high market share, and that happened in the late ’80s and early ’90s as a result of failures. There were so many mid-sized banks in this area that went out of business, and the U.S. Justice Department let the larger institutions pick up the troubled ones. The statistics I have seen show Rhode Island is the most overconcentrated market. In the Greater Providence area, the three largest competitors have about 81 percent market share. That’s absolutely extraordinary. The kind of experience that the rest of the country is going through in terms of consolidation, Rhode Island went through 10 years ago.
Q. What does it mean for a market to be so concentrated?
A. It’s had less of an impact here, but you start to see regional advertising, and it homogenizes the product set the customer sees on the retail side. On the commercial side, it is not to the advantage of this marketplace. Ironically, when the Justice Department looks at these things, it keeps focusing on consumers and deposits, but I think the bigger issues are on the business side, with businesses not only having access to financing, but having access to decision-makers and not simply being part of the statistical profile.
Q. Which brings us to your place in that market: BankRI has seized upon that and built a whole institution around it.
A. I think the numbers on our growth and our performance bear out that our original theory on being a business-oriented bank was well warranted. We were meeting a market need. If you look at the statistics, better than 95 percent of the businesses in Rhode Island have 100 or fewer employees. They are mid-sized to small businesses, and what they look to a bank to provide is not simply a product suite. Everybody has to be competitive on price, and we have always had the same product mix as the Fleets and Citizens of the world. But what we can do is know the customer far better, take the extra time. Small and mid-sized businesses tend to use their bankers, their lawyers, their accountants as trusted outside advisers. You may have two or three people trying to run a business, and they can use all the good advice that they can get.
Q. BankRI’s market share has grown by about 60 percent since you started. How much more can you take, and is it going to be primarily on the business end?
A. We have grown both on the business end and on the retail side, and I think that our potential is significant. I know some people talk about wanting to be No. 2; we’d like to be No. 3, and I think it’s a very achievable goal in the next five years, because the kind of approach we have toward customers is materially different from the competition. We’ve never depended on national economic growth to grow our commercial loans; what we depended on was being different enough from the big three so that we could take market share away from them. We depend on providing service, high touch, be there for the customer.
Q. To some extent, though, your success is tied to the success of business in Rhode Island.
A. Absolutely. The more we can do to foster a healthy business climate in this state, to attract new business, to ensure businesses here do well … no question: The better Rhode Island is, the better off we are.
Q. How is Rhode Island?
A. Rhode Island is not bad. I mean it’s not great; it’s not bad. It’s grown at a pretty modest clip, and I think we’re still finding our way as a state economy. We have what I call an institutionally driven economy. When people start focusing on the meaning of Brown University, RISD, Johnson & Wales, Providence College, it’s absolutely phenomenal. The other underrated sector is hospitals. The quality and size of the hospitals we have here is extraordinary, and their employment capacity is significant. You add to that some of the synergies you’re seeing with the Brown Medical School, biotech development and the research going on at some of the hospitals, you start to layer in those kinds of spinoffs and factors, and it creates a model that’s different from where we’ve been in the past. I can’t exactly predict where it’s going, but it’s very positive.
Q. Do you think Rhode Island makes the most of those resources?
A. No, but that’s our challenge, isn’t it? There’s another sector of the economy which I think is enormously underrated: art and design. We are spinning off artists and designers and design firms that have national if not international reputations, and they bring the kinds of jobs here that rely on people’s skill, that are not replicable easily someplace else. We need to use our intellectual horsepower.
Q. What about business climate? Is Rhode Island a business-friendly state?
A. We are not as business friendly as we should be, and it’s a source of enormous frustration. When I look at the state Legislature, there are so many people of good will who want to do the right thing, but they’re not businesspeople. In the last legislative session, there was an enormous amount of time spent discussing the casino, and the Mesolella hotel. And if we want to create more jobs for waiters, and waitresses and busboys, with high-salaried people being the dealers at the blackjack table, then let’s keep talking about casinos. If we could spend the same amount of time talking about economic development initiatives, and where the world is going, and how we can capitalize on the phenomenal skills we have here, we’d be hitting the cover off the ball.
Q. You are very active in the nonprofit sector. How has the consolidation in the banking market affected your experience with nonprofits?
A. I think the nonprofit and civic sector is suffering from the consolidation of the banking industry and other industries. Having corporate headquarters (in the state) has a ripple effect: it populates your boards of directors with executives who are not only knowledgeable about business practices, but are also a source of charitable contributions directly and indirectly, because companies that are located in a community tend to focus on that community and try to make it a better place.
Q. Where do you see BankRI in the next few years?
A. We’ve announced some big plans for the bank. We love our marketplace; we love our market niche. Over the next three to five years we’re looking at putting some six new branches on the map, in a variety of locations. … We have also repositioned our executive management; I could not be more excited about that. … We are positioning ourselves to smartly manage our balance sheet in the best interest of the shareholders, as well as give us the resources to sustain what has been extraordinary growth. … I cannot begin to tell you the kind of resources we see ourselves focusing on our commercial lending and the relationship-building aspect of that. That’s what distinguishes us from the next guy: really nice, soft-touch, high-touch good service. We’ve got a lot of growing to do.