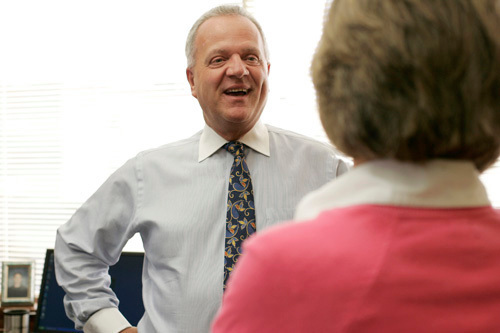
The 27,000 Rhode Island members of Coastway Credit Union will decide in April whether the credit union will re-establish itself as a mutual savings bank, a conversion that President and CEO William A. White said would better position the institution to grow.
“Back about five years ago, we started to feel some growing pains associated with some of the regulation that you have to endure as a credit union,” White said in an interview last week. “Credit unions are more heavily regulated than banks and some of the growth that we wanted to continue was being infringed upon. The regulation was holding us back a little.”
So in July 2008, the credit union filed a notice of intent with the National Credit Union Administration (NCUA) – the sister organization to the Federal Deposit Insurance Corporation (FDIC) – to convert to a mutual savings bank.
NCUA granted regulatory approval for the change in late December. Coastway now is in the process of mailing notifications before a special voting meeting, which is set for April 29. The last notification, which will be mailed in March, will include a ballot for each of credit union member.
“We have made our case to our customers – that we need to grow and we’re confident that they’re going to support us in this,” White said, adding, “They’ve been tremendously supportive.”
Headquartered in Cranston, the credit union has seven branches and about $300 million in assets, White said.
Much of the decision to convert to a bank can be traced to Coastway’s growing small-business and mortgage lending, he said. The company’s five-year business plan “shows that we can grow profitably while retaining that community-bank flavor. This is not about becoming the next big bank,” he added.
He said Coastway’s target is a 5 percent to 8 percent growth rate over the next five years. The company’s net income last year was about $1.2 million, down from about $1.8 million the year before.
Last year, Coastway’s small-business loans totaled about $15 million, with an average size of about $300,000. Coastway lends only to small businesses – that’s something that wouldn’t change with a conversion to a bank, he said.
“We lend to the local pizza parlor, the local distributor,” White said. “And we’ve done some high-tech lending recently.” AVTECH Software Inc., for example, financed its renovation of its new headquarters at Cutler Mills in Warren through Coastway.
White added that Coastway’s mortgage lending hit about $68 million last year. “And this year, we are on target to increase that by probably almost 50 percent,” he said. “We’re finding that there is a tremendous market out there.”
Long before they were the cause of turmoil in the financial and real estate markets, the credit union made a decision not write any subprime mortgages. “We had made a decision years ago that that was not a sound line of business to get into,” White said.
He added that the switch will allow Coastway “to do more of every kind of lending, which, if you follow the bouncing ball, leads to more net income for the bank, which we will continue to use as we have in the past. We will continue to reinvest it back into Coastway.”
That investment can be seen in both technology and physical infrastructure. The bank’s electronic banking has grown over the years to be White’s “second biggest expense, behind payroll.” And the company last year spent $1.5 million to buy The Washington Trust Co.’s Washington Street building in Providence. After a renovation of that building – set to start this summer and to take between six and nine months – Coastway’s downtown branch will move there from its current location on Greene Street.
“Right now, it’s the ugliest building on the street,” White said of the Washington Street facility. “When we get done with it, it will fit into the neighborhood. And I gain a drive-through and plenty of parking.”
One of the credit union’s other main goals, he said, has been to open new branches for customers. That growth – including potential branches in Coventry, East Greenwich and Johnston – would be dependent on a growing loan portfolio, White said. But the NCUA has strict regulations “that we have for three years been bumping up against … and are unable to make some of the loans that we wish we could make,” White said.
Those regulations “kind of hearken back to the old days of credit unions, where there used to be one-employer shops,” White said. “There’s no good business reason for them to have those restrictions on them. Coastway for years has been an active small-business lender, annually we are ranked in the top three of all U.S. Small Business Administration lenders in the state of Rhode Island.”
Coastway was organized in 1920 as the Telephone Workers’ Credit Union. It expanded to include the general population in 1976; in the 1980s, it changed its name to Coastway Credit Union; and in March 2000, it merged with Warwick Credit Union, where White had been president. At that time, the credit union had about 70 employees and a headquarters in Providence. Now, Coastway has 125 employees and is headquartered in Cranston.
As a credit union, Coastway is owned by its depositors: each member owns one share of Coastway, and each share is worth one penny. And as an FDIC-regulated mutual savings bank, its form of ownership wouldn’t change: each member would still have one vote. “If you have $1 million with me and [somebody else] has $1 with me, your vote is the same,” White said. •
ISO 9001:2026: A Practical Opportunity to Build for What’s Next
For Rhode Island manufacturers, ISO 9001 has been much more than a certificate on the…
Learn More